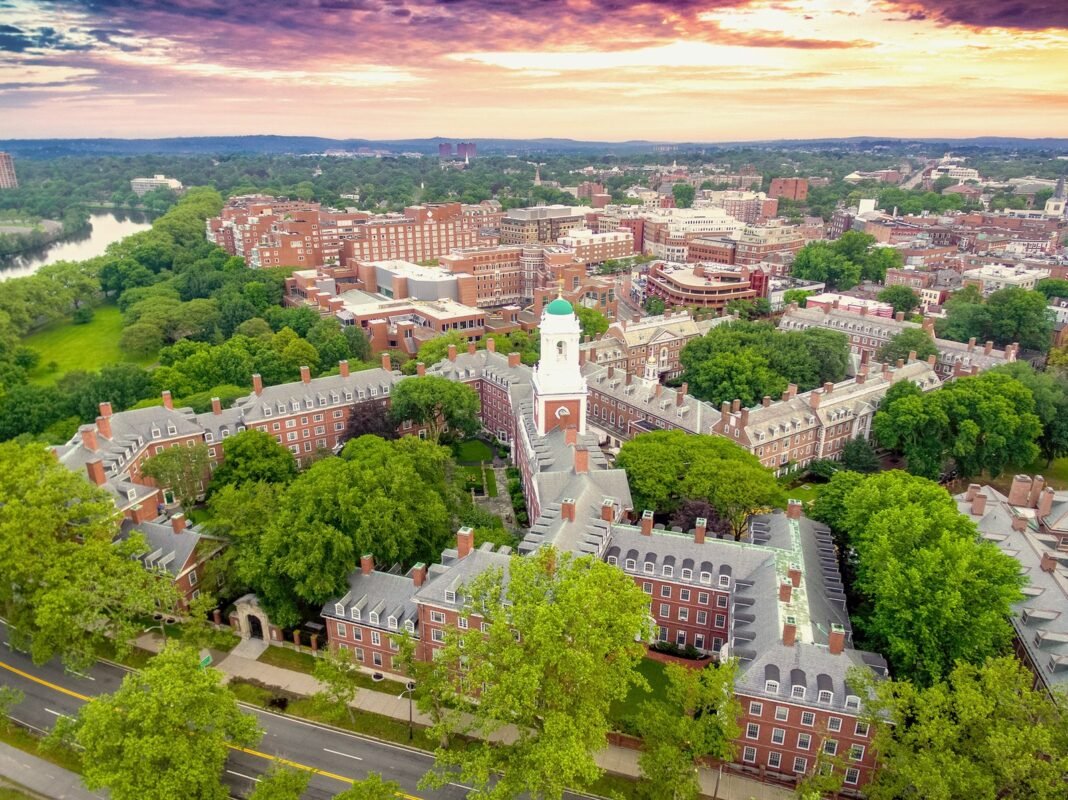


The Harvard endowment posted a 27.1 percent return for fiscal 2026, lifting the university’s investment fund to a record $68 billion, according to Harvard’s annual financial report released Thursday — the endowment’s strongest performance in five years.
The result beat the S&P 500’s 22.3 percent total return over the same period by 4.8 percentage points and came in far above the roughly 18.9 percent median for large endowments. The Harvard endowment grew by about $11 billion from a year earlier, snapping a stretch of mid-single-digit returns.
The standout driver was SpaceX. Harvard Management Company, which runs the endowment, disclosed a $2.2 billion stake in Elon Musk’s rocket and satellite company in its second-quarter 13F filing with the Securities and Exchange Commission — its single largest holding by value, trailed by Taiwan Semiconductor Manufacturing Company at just under $350 million.
SpaceX went public in June 2026, just before the fiscal year closed, in an offering described as the largest initial public offering in history, valuing the company at more than $1.8 trillion after its debut. The listing turned Harvard’s long-held private position into a liquid public holding. The stock has since traded lower: shares closed at $148.62 on October 15, about 7.7 percent below their first daily close on June 12 and well under the $225.64 52-week high.
How the Harvard endowment rode SpaceX and AI to a record
HMC chief executive N.P. ‘Narv’ Narvekar credited the results to strong performance across venture capital, public equities and hedge funds, and the Harvard endowment’s public disclosures show a deliberate tilt toward space and artificial intelligence hardware.
Beyond SpaceX, the endowment opened a position worth about $239 million in AI chipmaker Cerebras Systems and significantly increased its holdings in Nvidia and TSMC, two companies at the center of the AI hardware supply chain. In August, Harvard disclosed that its SpaceX stake alone made up more than half of its $4.3 billion U.S. equities portfolio.
Harvard’s fiscal year ends June 30. In the school’s 49-page annual report, chief financial officer Ritu Kalra and treasurer Timothy Barakett wrote that ‘while markets can easily take back what they give, that return will strengthen the endowment’s capacity to support the University over time,’ adding that the university deliberately smooths distributions so operating support does not swing with the markets.
Peer institutions including Yale, Princeton and Stanford are expected to release fiscal 2026 results over the next 45 days, with early signals pointing to a performance band between 18 and 24 percent — well short of the Harvard endowment’s mark and a reminder of how much concentration contributed to the outperformance.
Federal pressure shadows the Harvard endowment’s big year
The strong investment results arrive against a difficult financial backdrop. The Trump administration has sought to penalize Harvard and withhold funding over policy disputes, and federally sponsored research revenue fell 19.5 percent to $509 million in fiscal 2026. Even in a record year, the Harvard endowment cannot replace lost federal research dollars one-for-one.
A larger structural threat is the federal excise tax on net investment income. Starting in the current fiscal year, the rate applied to Harvard’s endowment rises nearly sixfold, from 1.4 percent to 8 percent. Kalra and Barakett estimated the higher rate will cost roughly $300 million a year — and ‘several times larger’ in a year of returns like fiscal 2026.
The tax bite explains why endowment officials treat banner years as balance-sheet repair rather than spending windfalls. After two lean years, the fund’s three-year annualized return remains below 10 percent, a drag that still constrains long-dated commitments to financial aid, faculty hiring and research facilities.
What the record Harvard endowment means going forward
For now, the $68 billion milestone cements Harvard’s position as the world’s wealthiest university endowment and offers a case study in concentration. The traditional endowment model preaches broad diversification across vintage years and sectors; HMC instead let a single name dominate its public book, betting that Musk’s enterprise value would compound faster than the broader market.
Whether the Harvard endowment’s concentration keeps paying will depend on SpaceX’s trajectory as a public company and on the AI hardware cycle that powered the rest of the portfolio. Endowment distributions are smoothed over multi-year formulas, so the fiscal 2026 windfall will feed Harvard’s operating budget gradually rather than all at once.
For alumni, donors and rival institutions watching the Harvard endowment, the lesson of fiscal 2026 is that scale plus conviction can still beat the median by eight percentage points — but the federal tax bill arriving this year will test how much of that outperformance Harvard actually gets to keep.